Nº 21 · 11 Jun 2026
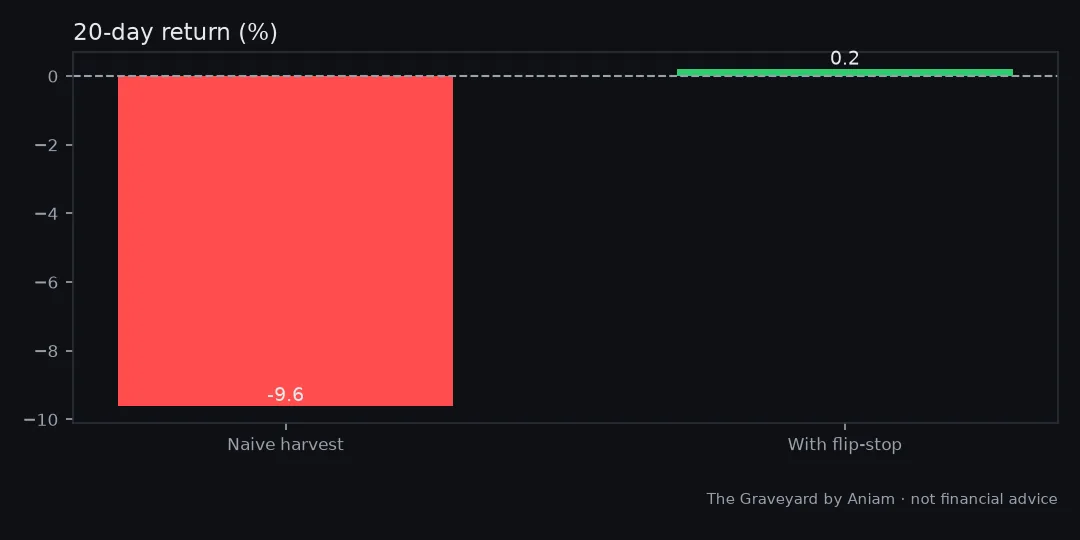
Funding carry: '40% a year' became -9.6% in 20 days
- Worst coin
- -61%
- Best case, flip stop, 20 days
- +0.2%
With an exit-on-negative-funding rule it roughly breaks even: +0.2% in 20 days.
Read the autopsyclaim · method · every number · the raw chart
Source: Delta-neutral funding harvest, widespread
One coin's funding flipped and it bled 61%.
The headline yield is mostly the risk of funding flipping on you.
This verdict is about the strategy as published, not about the person who shared it.
The claim
Here’s what the strategy promises, in its own terms.
Short the perp, hold spot, collect funding on the highest-paying coins.
How we tested it
Same six checks as everything else here: random entries, coin flips, a look-ahead audit, unseen years, double costs and a luck check. How we test →
What we found
Out-of-sample on real exchange funding: pick the highest-funding liquid coins on one half of the data, hold them through the other half. The basket lost 9.6% in 20 days; one coin paid well, then its funding flipped and it bled 61%. A single rule, exit the moment funding turns negative, capped that to -0.2% and made the basket +0.2% over 20 days, about 4% a year. Real, mechanical, and modest.
The numbers
The headline numbers from our test.
| Naive 20-day return | -9.6% |
|---|---|
| Worst coin | -61% |
| With flip stop 20-day | 0.2% |
| With flip stop annualised | ~4 |
- Profit factor: money won divided by money lost. Below 1.0 loses money. Around 1.0 is break-even.
- R-multiple: profit or loss measured in units of the amount risked per trade. +1R means you made what you risked.
- vs random: how the strategy did against the same trades with random entries.
You’re on the list.
Your first issue arrives with the next weekly send. Until then, the graveyard is open.